Retail Finance Operations: Closing the Gap Between Purchasing, AP, and Cash Flow
Learn how connecting purchasing commitments, accounts payable, and 3-way matching optimizes retail cash flow visibility.
Retail finance teams can know what has already been purchased without having an equally clear picture of when those purchases will affect cash. A purchase order may be created weeks before an invoice reaches accounts payable, while payment planning may happen somewhere else. Between those events are receiving, invoice review, matching, approvals, and payment scheduling.
This creates a practical visibility gap. Procurement sees commitments being made, AP sees invoices arriving, and finance sees the current cash position. The connection between those pieces often has to be reconstructed manually.
Retail makes this particularly important because purchasing can involve many suppliers, frequent orders, different payment terms, and seasonal changes in demand. When purchasing records, AP information, and cash planning are separated, finance may not see the full effect of purchasing activity until much later.
The result is not necessarily a major system failure. It is often a collection of small manual tasks: exporting purchase data, checking invoices against separate records, updating spreadsheets, and trying to estimate future payments. Together, those gaps make cash flow management harder than it needs to be.
Answer Snippet
Connecting purchasing commitments, accounts payable processing, 3-way matching, and scheduled payments gives retail finance teams earlier visibility into cash flow. By automating 3-way matching and syncing payment schedules with actual commitments, retailers manage working capital more accurately.
Key Takeaways
- Purchasing commitments represent future cash outflows long before vendor invoices land in accounts payable.
- 3-way matching connects purchase orders, goods receipts, and invoices to catch pricing or quantity discrepancies early.
- Disconnected retail finance systems result in manual spreadsheet tracking, delayed cash forecasting, and unexpected liabilities.
- AI-driven invoice processing and automated reconciliation streamline high-volume retail transactions while preserving human review for exceptions.
- Supplier performance and payment terms heavily influence cash visibility during seasonal retail demand spikes.
Where the Gap Between Purchasing and Finance Starts
The financial impact of a purchase begins when the commitment is made, not when the supplier's invoice arrives.
A purchase order contains information that can help describe a future obligation: the supplier, agreed price, payment terms, expected delivery, and quantity. If that information remains visible only to procurement, finance has less information available for cash flow forecasting.
This becomes more noticeable when retailers place large numbers of orders around seasonal demand. Different suppliers may have different payment arrangements, and some purchases may require deposits while others are payable after delivery.
Giving finance visibility into purchase commitments earlier creates a better starting point for understanding future cash requirements. Instead of waiting for invoices to reveal what has already been committed, finance can consider purchasing activity as part of the broader cash picture.
Connecting Purchasing With Accounts Payable
Once an order has been placed, the transaction usually moves through receiving and invoicing before AP can approve it for payment.
A typical sequence is:
Purchase order → Receiving → Invoice → Matching → Approval → Payment
The challenge is making sure AP can access the information created earlier in that sequence. An invoice should not have to be evaluated in isolation when the purchase order and receiving information already provide useful evidence about what was ordered and what arrived.
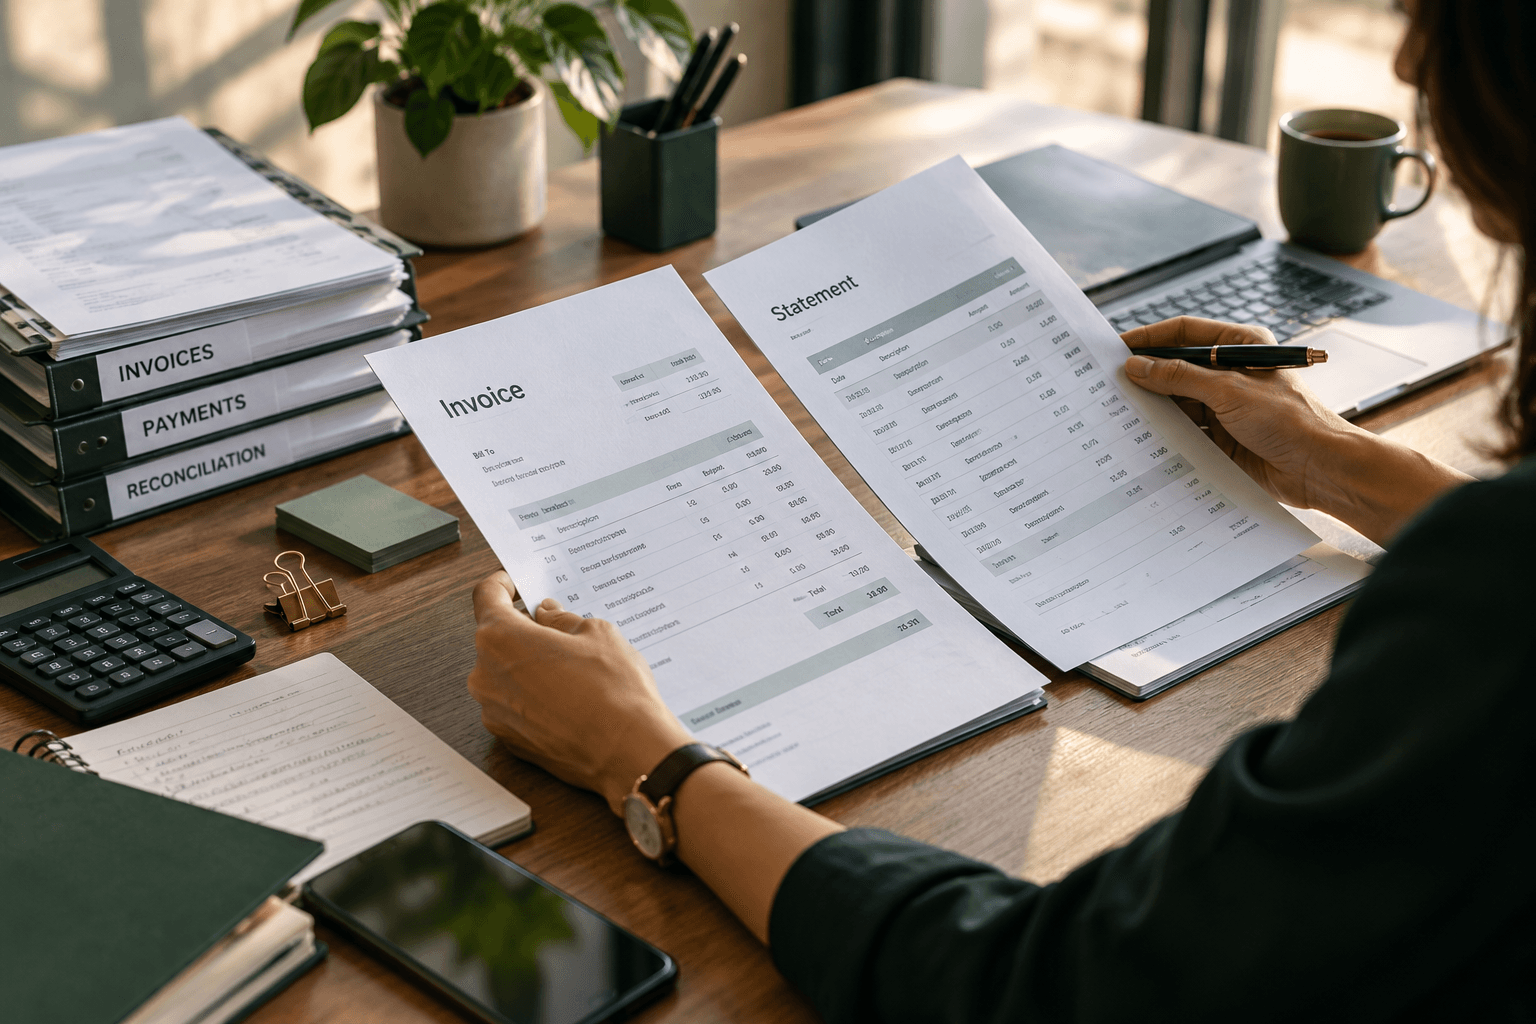
Invoice processing can begin by extracting relevant information such as supplier details, amounts, line items, and payment terms. Validation can then check whether the information is complete and consistent. Matching connects the invoice back to the purchase order and, where applicable, the receiving record.
When the purchase order, receipt, and invoice are compared together, this is commonly known as 3-way matching. It gives AP a way to identify differences before an invoice moves toward payment.
After validation, approval routing can send the transaction to the appropriate person according to internal rules. The approved invoice can then enter payment scheduling.
From Approved Invoice to Cash Outflow
Approval does not mean the financial impact has ended. It means the organization has accepted an obligation that will eventually become a cash outflow.
Payment terms determine when that outflow is expected. A supplier may require payment immediately, after 30 days, after 60 days, or according to another agreed arrangement. For finance, the important question is therefore not only how much has been approved, but when the money is expected to leave.
When approved invoices are connected to their expected payment dates, finance has more concrete information for cash-flow planning. Instead of relying entirely on historical assumptions, the team can consider specific obligations that are already moving through the process.
Payment automation can also help maintain the intended schedule by reducing the chance that an approved invoice sits untouched because someone has to remember the next manual step. This can help avoid unnecessary late payments while preserving visibility over upcoming outflows.
Why Retail Needs Better Cash Visibility
Retail purchasing often involves a large number of supplier transactions and changing demand patterns. Seasonal periods can increase purchasing well before the corresponding sales occur, meaning cash may be committed before revenue from that inventory is realized.
Supplier terms also differ. One vendor may allow extended payment terms while another may expect payment much sooner. At the same time, purchasing requirements can change as demand changes.
These conditions make it difficult to understand future cash requirements when purchasing and AP information are maintained separately. A complete view needs to account for both what the business has already purchased and what invoices have progressed toward payment.
Better cash visibility does not require removing the existing purchasing or AP processes. It requires bringing the relevant information together so finance can understand how current commitments affect upcoming cash requirements.
Using Supplier and Purchasing Data to Improve Decisions
Purchasing decisions become more informed when buyers can see historical supplier information rather than evaluating every order on the current quotation alone.
Previous pricing can help identify whether a new quote is consistent with past purchases. Payment terms can reveal the cash implications of choosing one supplier over another. Delivery history can provide additional context when a buyer is considering a supplier whose lead times have been inconsistent.
This information can also help finance understand the cash consequences of supplier relationships. Two suppliers offering similar prices may create different cash requirements because their payment terms differ.
Connecting purchasing history with supplier information therefore benefits both sides. Procurement gets more context for sourcing decisions, while finance gets a clearer view of the factors that influence future obligations.
AI and Automation Across Retail Finance Operations
Automation is most useful when it removes repetitive coordination from an existing finance workflow.
For example, intelligent document processing can extract information from incoming invoices so employees do not have to manually enter every field. That information can then be checked against purchasing and receiving records as part of the matching process.
Automation can also help identify exceptions. A transaction with matching information can continue through the normal workflow, while an unusual price, quantity, or payment-term difference can be brought to a person's attention.
Approval routing and payment preparation can follow the same model. Routine transactions can move through defined steps, while exceptions are separated for human review. Reconciliation can also benefit from automated matching between payments and the records they are intended to settle.
AI agents can assist with gathering information, comparing records, and preparing context for review. They should not be presented as replacing the people responsible for financial decisions. Human approval remains important when an exception requires business judgment.
A Practical Retail Workflow: From Purchase to Cash Flow
Consider a retailer preparing its inventory for a seasonal change. A buyer orders products from an established supplier under agreed pricing and payment terms.
The purchase order is created first. When the shipment arrives, the receiving team records the quantities received. Later, the supplier sends an invoice.
During matching, the invoice shows a unit price that is different from the purchase order. Instead of allowing the invoice to proceed automatically, the difference is identified and sent for review.
The buyer or appropriate manager can then determine whether the price difference was authorized, caused by an error, or requires the supplier to issue a corrected invoice. Only after the issue is resolved does the transaction continue through approval and payment scheduling.
Once payment is made, the payment can be reconciled against the invoice and related records. The expected payment date can also be included in the retailer's cash outlook.
The important part of this workflow is the connection between the stages. Procurement, AP, payment, and reconciliation are working from related transaction information rather than treating each stage as an isolated activity.
What Happens When These Processes Stay Separate?
Disconnected workflows create additional work because employees have to supply the connection themselves.
Purchasing information may be exported into a spreadsheet for finance. AP may separately export invoice information to compare it with purchasing records. The same supplier or transaction details may be entered more than once.
These manual processes also introduce timing problems. AP may need to confirm information that procurement already reviewed. Procurement may make another purchasing decision without seeing the full set of existing payment commitments. Finance may only discover a significant obligation once an invoice has progressed far enough to become visible in the AP process.
Reconciliation becomes harder when related records are not connected from the beginning. Cash forecasting can also become less reliable when purchase orders, approved invoices, and scheduled payments are stored in different places.
The issue is therefore not simply the number of systems. It is the amount of work required to connect the information between them.
What Connected Retail Finance Operations Look Like
A connected model allows information to remain associated with the transaction as it moves through the workflow.
Purchasing creates the initial commitment. Supplier information, pricing, and terms provide context for that decision. The purchase order becomes available to the teams that need it. Receiving records what actually arrived. AP can compare the invoice with the earlier records before approval. Payment scheduling establishes when the obligation is expected to affect cash. Reconciliation then confirms what happened when the payment is processed.
The individual tasks do not disappear. What changes is the amount of manual effort required to move information from one stage to the next.
This gives procurement and finance different views of the same underlying transaction instead of forcing each team to reconstruct its own version.
How Rotasu Helps
Rotasu is designed around connected finance workflows, with procurement, accounts payable, document processing, and reconciliation capabilities presented as parts of a broader operating flow.
For procurement, Rotasu presents RFQ distribution and side-by-side vendor comparison using information such as pricing, lead times, and supplier performance. Its purchasing workflows are also presented with inventory information in mind, helping connect purchasing decisions with the conditions that influence them.
For AP, Rotasu's presented document workflow captures and validates invoices and supports matching against purchase orders, goods received notes, quality-check information, and purchase requisitions. The workflow supports 2-way and 3-way matching, policy checks, approval routing, exception detection, and smart data autofill for information such as line items, categories, tax calculations, and vendor pricing.
Rotasu also presents automated reconciliation capabilities, including many-to-many matching across bank, vendor, customer, and payment information. Exceptions can be surfaced with suggested corrections and an audit trail.
Its integration catalog presents systems including SAP, Oracle NetSuite, Microsoft Dynamics 365, QuickBooks, Xero, and Sage. These integrations are presented as part of the product's connected operating model rather than as evidence of backend connector implementation in the current website repository.
The broader purpose is to connect the stages between a purchasing decision, AP processing, reconciliation, and the financial information teams need to review, while retaining human involvement where approval or judgment is required.
Conclusion: Connecting Purchasing, AP, and Cash Flow
Purchasing, AP, and cash-flow planning affect the same financial activity, even when different teams manage each stage.
When purchase commitments are visible earlier, finance has more information to use in planning. When AP can access purchasing and receiving context, invoice verification becomes easier. When approved obligations are associated with expected payment dates, cash planning can be based on actual commitments rather than broad estimates.
The objective is not to remove finance professionals from the process. It is to reduce the manual work required to connect information that already belongs to the same transaction.
For retail organizations, bringing purchasing, AP, payment, and reconciliation information into a connected workflow can give finance and procurement a clearer view of what has been committed, what still needs attention, and what those decisions may mean for cash.
Frequently Asked Questions
What is retail finance operations?
Retail finance operations covers the financial workflows surrounding activities such as purchasing, accounts payable, invoice processing, payment scheduling, reconciliation, and cash visibility. Connecting these activities can make it easier to understand how purchasing decisions affect financial obligations.
How does procurement affect retail cash flow?
A purchase order creates a future financial commitment even before the supplier sends an invoice. The price, quantity, supplier terms, and expected payment timing can therefore influence future cash requirements from the point the purchase is approved.
How can AP automation improve cash visibility?
AP automation can speed up invoice capture, validation, matching, and approval workflows. When approved invoices are associated with payment schedules, finance can obtain a clearer view of upcoming obligations.
Why should purchasing and AP workflows be connected?
Purchasing creates the information AP needs to validate supplier invoices. Connecting the workflows allows AP to compare invoices with purchase orders and receiving records without repeatedly searching for information in separate systems.
How can AI improve retail finance operations?
AI can assist with repetitive activities such as extracting invoice information, comparing records, identifying exceptions, and preparing information for review. Human finance professionals should remain responsible for approvals and decisions that require judgment.
What role does ERP integration play in retail finance?
ERP integration can help connect purchasing, accounting, and other financial information with systems already used by the organization. The objective is to reduce repeated data movement and provide teams with more consistent information.
How does reconciliation affect cash-flow visibility?
Reconciliation checks whether actual payments correspond with the financial records they are expected to settle. Reliable reconciliation helps finance distinguish completed transactions from outstanding or unresolved items.
Can finance automation reduce manual work?
Yes. Activities such as invoice capture, matching, exception identification, and reconciliation can contain repetitive steps that are suitable for automation. The purpose is to reduce administrative effort while preserving human review for important exceptions and decisions.